



Week of 26 October – 2 November 2026 · FinTech
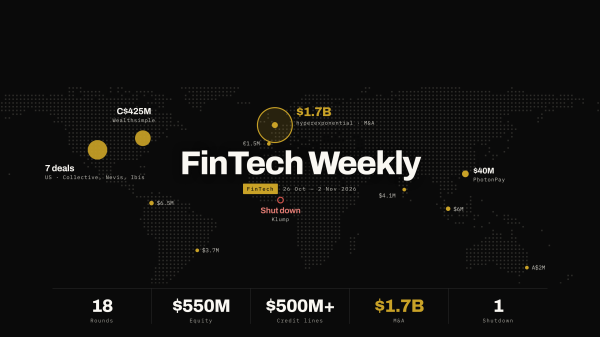
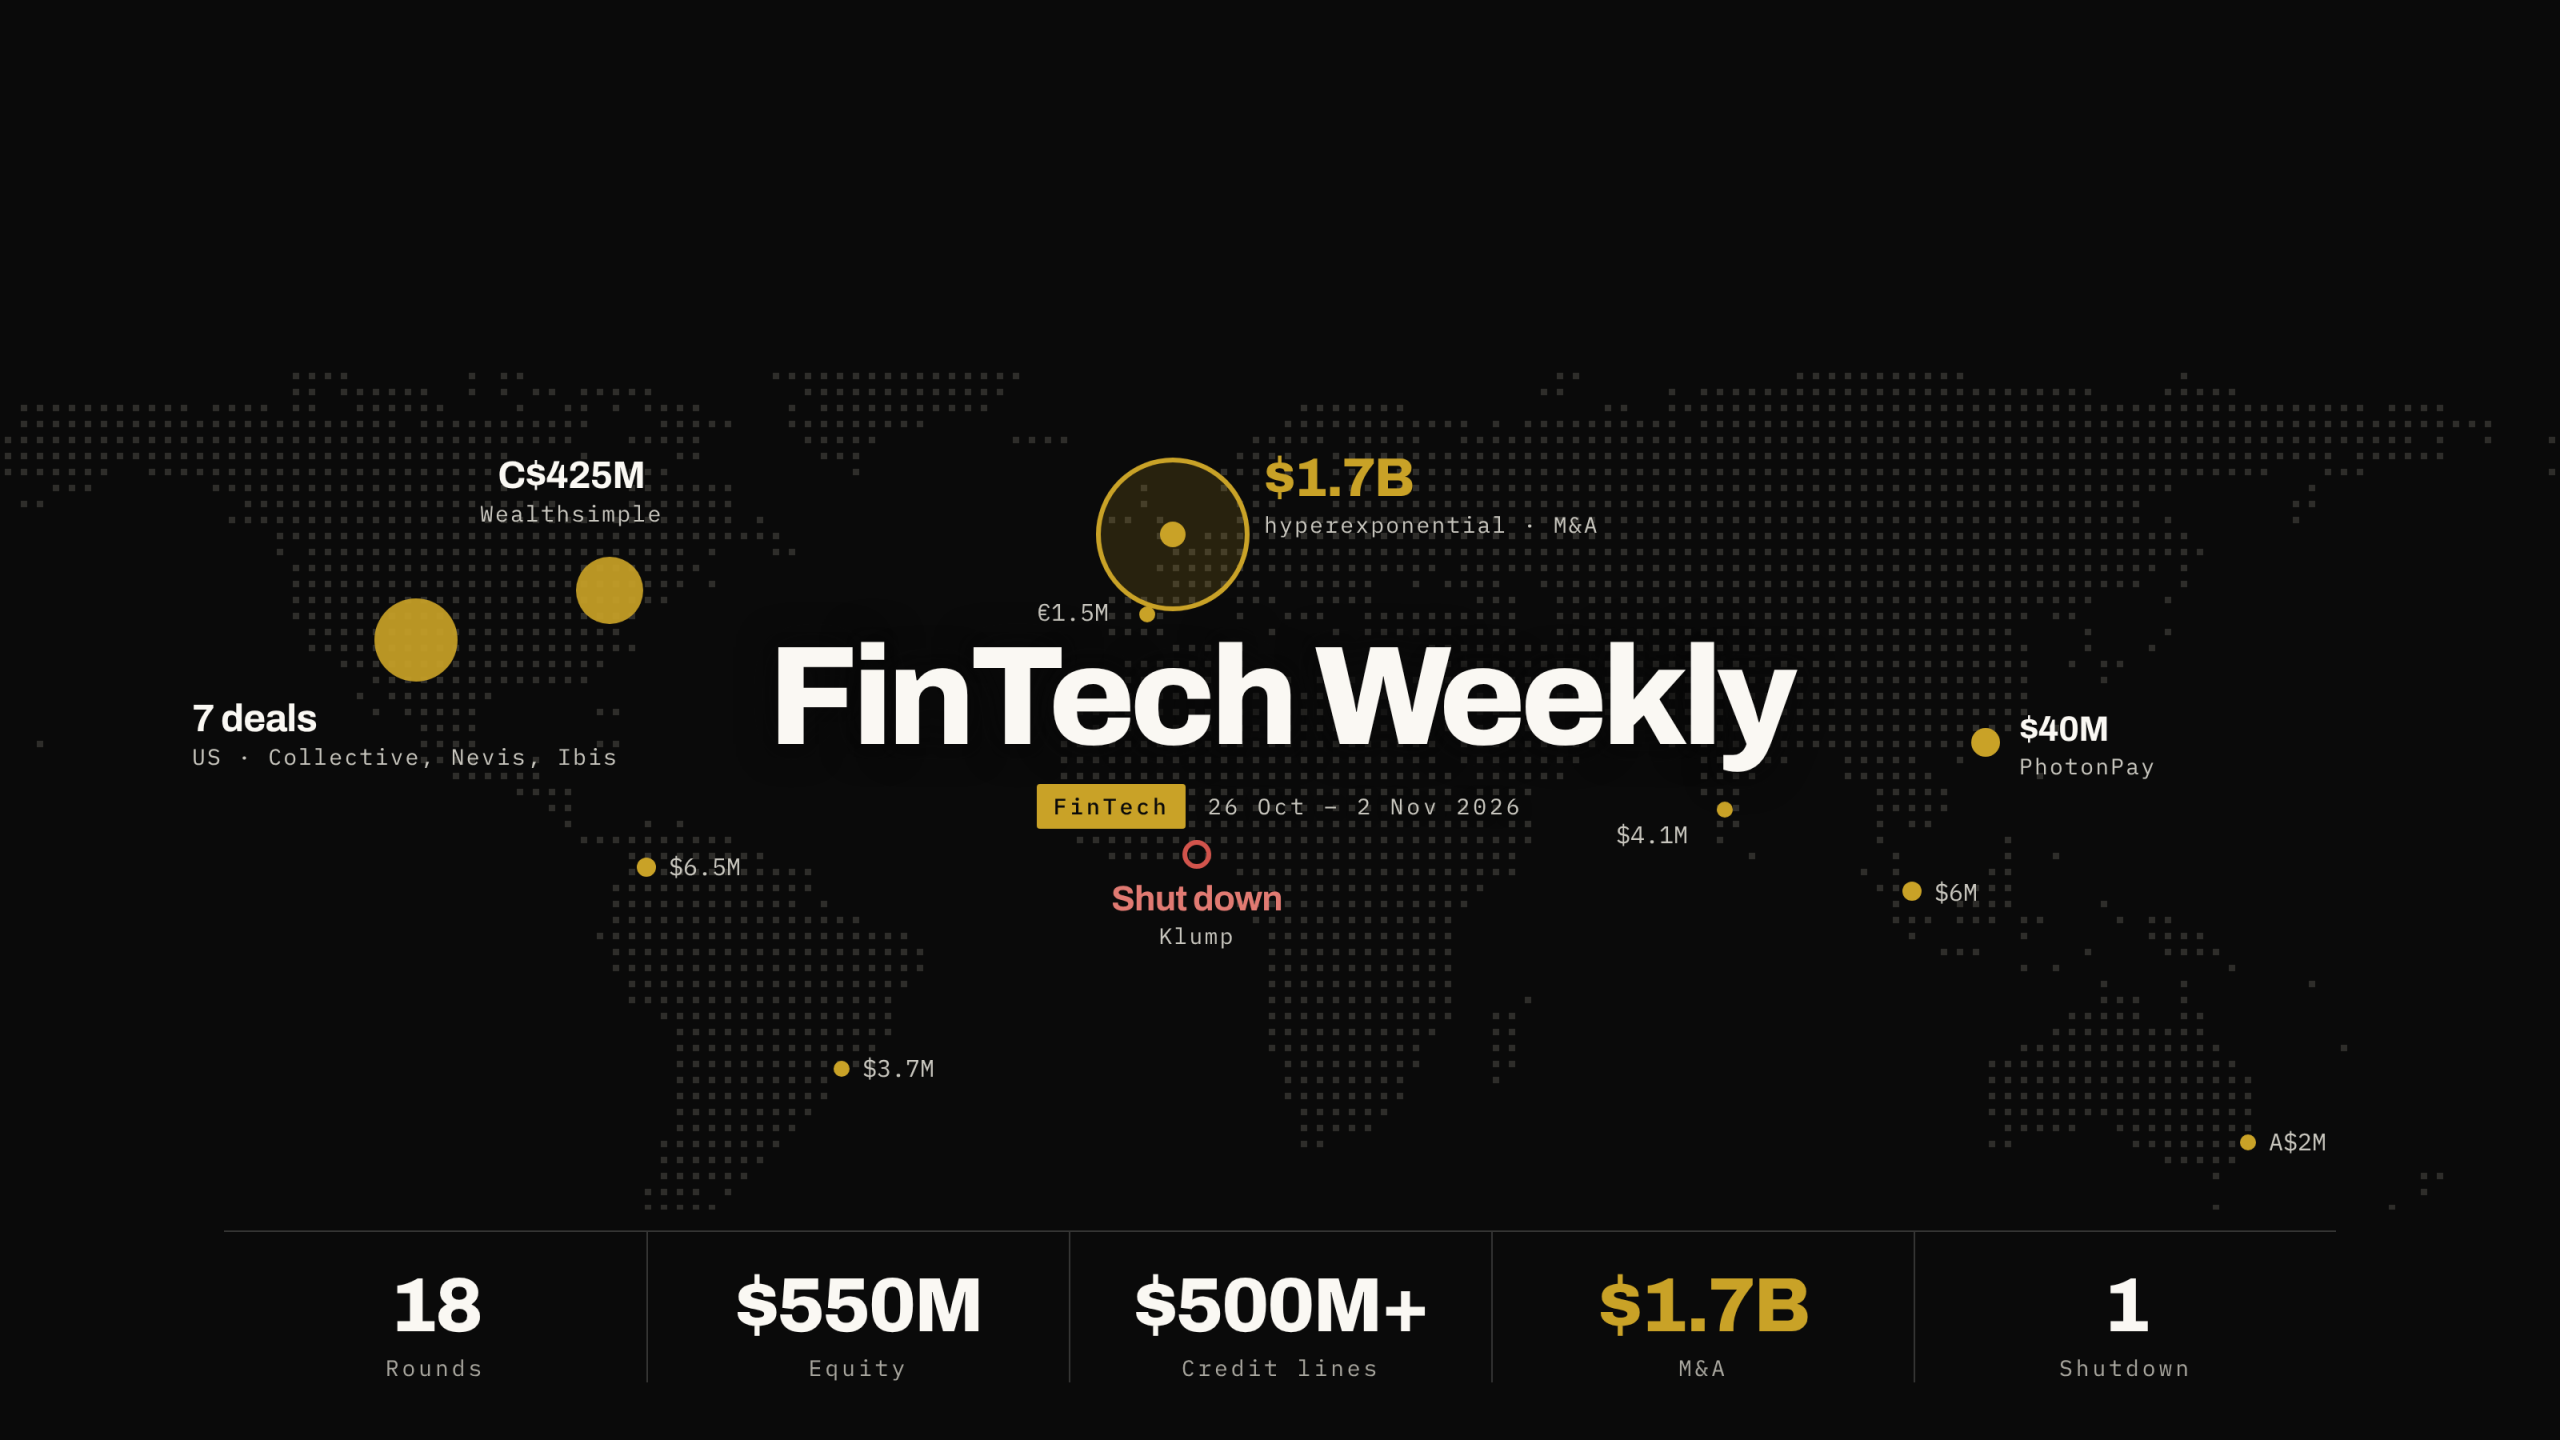
This week brought 18 rounds with about $550M in equity, over $500M in new credit lines, one $1.7B acquisition and one shutdown. Last week’s theme continued: AI agents are taking on finance work, now including wealth advisers, trusts, insurance brokers and one-person businesses. The biggest deal was in insurance: Guidewire’s purchase of London’s hyperexponential. Lenders also handed out more than companies raised in equity, through new credit lines.
THE DIGEST
🇨🇦 Wealthsimple raises up to C$425M at a C$13.8B valuation
Singapore’s sovereign wealth fund GIC led the round, with Power Corporation, IGM Financial, ICONIQ, CPP Investments and Inovia returning. Of the total, C$300M is new money for the company and up to C$125M lets employees sell shares. The valuation is 38% higher than a year ago, and assets on the platform have grown to C$169.2B, up from C$100B at the last raise.
🇺🇸🇬🇧 Nevis raises a $70M Series B (€62M) for AI that does wealth advisers’ admin
EQT Ventures led the round, with Charles Schwab joining as a strategic investor and QuantumLight, Revolut CEO Nik Storonsky’s fund. Sequoia, ICONIQ and Ribbit returned. Nevis was founded two years ago by three former Revolut executives and has raised $110M so far. Fortune reports a $500M valuation, though Nevis hasn’t confirmed it. Its roughly 20 customers include Focus Financial Partners, and assets on the platform have grown from $50B to $700B this year.
🇺🇸 Hyphenate raises a $45M Series A after 86x revenue growth
Nexus Venture Partners led the round, with B Capital and existing investors Foundation Capital, BoldCap and Gaia. Formerly called Maximor, the company was founded by two former Microsoft finance-transformation colleagues. Its AI agents do routine finance-team work such as reconciliation and invoicing. In the 13 months since its $9M seed, revenue grew 86x and customers 11x, including six public companies such as Groupon and Synthesia. ARR Club reports a $270M valuation.
🇺🇸 Collective raises $100M: a $40M Series B plus a $60M growth facility
General Catalyst, QED and Gradient Ventures led the equity, with Intuit Ventures and FT Partners. The $60M comes from General Catalyst’s Customer Value Fund and is earmarked for winning customers. Collective handles bookkeeping, payroll, taxes and insurance for one-person businesses. Its AI support resolves about half of customer requests on its own, and recurring revenue grew 120% year on year.
🇭🇰 PhotonPay raises a $40M Series C for business payments that mix stablecoins and regular money
Blockchain Capital led the round, with SBI Group joining and IDG, GL Ventures and Lightspeed Faction returning. PhotonPay processes about $65B a year in transactions and issued 4.4 million cards over the past year, up 275%. It completed a test payment initiated by an AI agent with Mastercard in May.
🇺🇸 Ibis launches with a $250M credit line from FalconX
FalconX, a crypto trading and lending firm, also led Ibis’s pre-seed round, with Anchorage Digital and Innovating Capital. Ibis lends through blockchain-based systems (“onchain”) to businesses traditional lenders struggle to serve, starting with crypto trading firms. It plans to expand into financing AI computing chips, robotics and venture capital.
🇺🇸 Sava raises a $10M seed for an AI-run trust company
Gradient Ventures led the round, with Y Combinator and SV Angel. Sava has launched a Nevada-chartered trust company that uses AI to handle trust paperwork, with human trust officers overseeing the work. It charges a flat annual fee per trust, which aims to make trusts affordable for smaller estates.
Also raising:
- 🇨🇴 FinMaq: $6.5M Series A led by Accion for small-business equipment loans. It has lent more than $100M since 2019 and aims to double that in 18 months.
- 🇬🇧 i23: £4.9M seed (Four Cities, Outward VC, Seedcamp) for AI that handles insurance brokers’ admin, founded by former UK minister Kemi Afolami
- 🇸🇬 CoverGo: $6M Series B1 for its AI insurance platform
- Mochatrade: $5.5M seed led by CoinFund for a trading platform
- 🇮🇳 Tradl: $4.1M seed from Nexus and Stellaris to give retail traders professional trading tools
- 🇺🇸 Birch Hill: $4M seed led by Multicoin to bring US farm, apartment and energy loans onto blockchains. Founded by Goldman Sachs and BlackRock alumni, it has applied to become a FINRA-registered broker-dealer.
- 🇺🇸 SpendRule: $4M seed led by Mark Cuban’s Radical Investments
- 🇧🇷 Bloquo: $3.67M seed for stablecoin payments
- 🇬🇧 Marrow: £1.49M pre-seed to connect AI agents to insurers’ systems
- 🇪🇸 Talky Labs: €1.5M pre-seed for AI that learns how accountants actually work (closed in September)
- 🇦🇺 Copy Geek: A$2M pre-seed for copy-trading software, which lets users automatically copy other traders’ trades
DEBT
- 🇬🇧 Lovey secures up to £250M (€298M) from Pollen Street Capital (£50M committed, plus £200M available later) for UK small-business lending. Lovey’s loan volumes doubled to £195M in 2025.
EXITS & M&A
🇬🇧🇺🇸 Guidewire agrees to buy hyperexponential for $1.7B in cash, plus up to $400M more if revenue targets are hit. The London company’s software helps insurers price and underwrite commercial policies, covering more than $75B in annual premiums for customers including Aviva, Allianz, Beazley and Markel. Guidewire is funding the deal with a $1B loan from Bank of America and Citi plus cash, and expects it to close by January 2027. It follows a GTCR-led group’s $6.1B deal this month to take CCC Intelligent Solutions private, as insurance software consolidates.
SHUTDOWNS
🇳🇬 Klump shuts down after five years. The buy-now-pay-later startup worked with Jumia and Konga, two of Nigeria’s largest online stores, and had raised $1.2M. Its founders blamed difficulty getting money to lend and slow, restrictive bank partners, and wrote that access to credit remains an unsolved problem.
THE ANALYSIS
1. AI agents keep taking over finance work
Hyphenate handles finance teams’ routine work, Nevis does advisers’ admin, Collective runs one-person businesses’ books, Sava manages trusts, and i23 handles brokers’ admin. The 86x revenue growth and $270M valuation suggest companies are now paying for this at scale, not just trialling it.
2. Insurance software is consolidating fast
Guidewire’s $1.7B purchase of hyperexponential is the week’s largest deal, coming weeks after the CCC take-private. Smaller insurance startups like i23, Marrow and CoverGo are building the layer that connects AI to insurers’ systems, which makes them obvious acquisition targets.
3. Debt outweighed equity in the headlines
Ibis got $250M, Lovey up to £250M, and Collective a $60M facility to pay for customer acquisition. Lending fintechs are scaling on borrowed money rather than equity. That’s cheaper for founders, but it depends on lenders, as Klump’s collapse shows.
4. Blockchain finance is moving into lending
Ibis and Birch Hill are both putting lending on blockchains, Birch Hill with a US regulatory application under way. PhotonPay shows stablecoin payments already work at scale; lending is the next step.
5. Wealth management is digitising
Wealthsimple raised at a 38% higher valuation, Schwab invested in Nevis, and Sava raised for trusts. Wealth management depends on advisers and paperwork, and that’s where AI is now being aimed.
6. In emerging markets, having your own lending capital matters
FinMaq has lent more than $100M with backing from Accion and lenders. Klump depended on partner banks for its lending money and shut down. In Africa and Latin America, lenders survive by controlling their own source of capital.
Bottom line: AI agents moved further into finance work, insurance software saw its biggest deal of the year, and lenders funded growth through credit lines. Wealthsimple’s raise shows top fintechs can still command large valuations, while Klump’s shutdown shows what happens to lenders without their own capital.